Roth Sweet Spot: The Little-Known Retirement Tax Strategy That Could Save Families Thousands in Lifetime Taxes

Paladin Retirement Advisors introduces the "Roth Sweet Spot," a retirement tax-planning window that may help retirees reduce lifetime taxes, lower future Medicare premiums, and create greater tax-free retirement income.
NEWTOWN, PA / ACCESS Newswire / August 11, 2026 / Many Americans spend decades focused on building wealth for retirement. It appears that far fewer spend time planning how to withdraw those assets in the most tax-efficient way possible. According to retirement advisor Jeff Beyer, Founder of Paladin Retirement Advisors, that oversight may become increasingly costly as retirees face a convergence of economic, demographic, and legislative factors unlike any seen in recent decades.
Beyer calls this unique planning opportunity the Roth Sweet Spot - a limited window that often exists after retirement but before Social Security benefits and Required Minimum Distributions (RMDs) begin. During these years, many retirees experience their lowest taxable income since entering the workforce, creating an opportunity to strategically convert traditional IRA assets into Roth accounts while potentially paying significantly lower taxes than they would later in retirement.
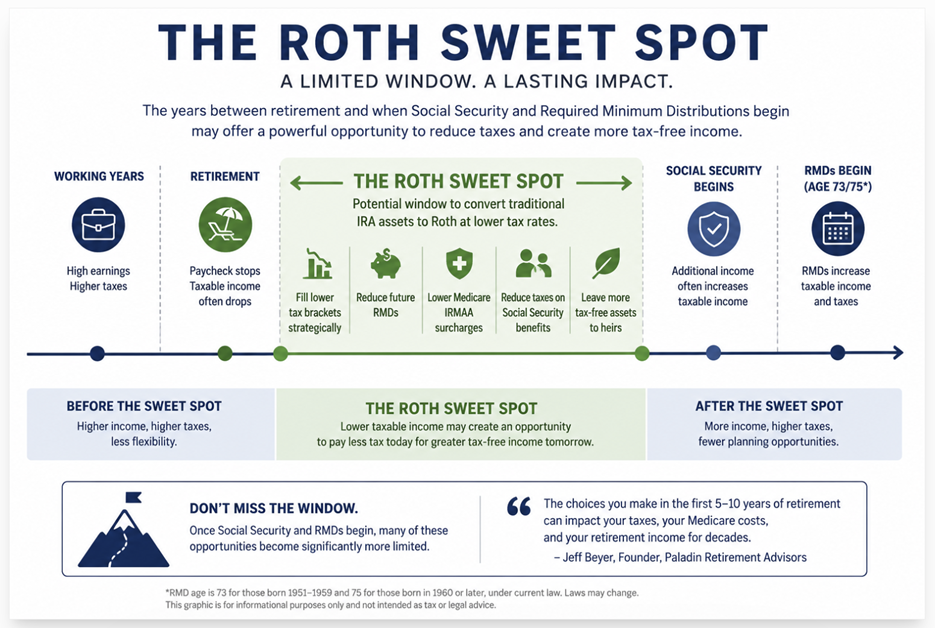
"It's rare that so many planning factors align at the same time," said Jeff Beyer. "Employment income has stopped, many retirees delay claiming Social Security to maximize future benefits, and Required Minimum Distribution ages have been pushed back under recent legislation. At the same time, today's federal income tax rates remain relatively low under current law. For many retirees, this creates what we call the Roth Sweet Spot-a limited opportunity to take greater control over their lifetime tax bill."
The strategy is built around intentionally filling lower income tax brackets during retirement's low-income years instead of waiting until Required Minimum Distributions force larger taxable withdrawals later in life. By strategically converting portions of pre-tax retirement accounts over several years, retirees may reduce future RMDs, lower Medicare Income-Related Monthly Adjustment Amount (IRMAA) surcharges, lessen the taxation of Social Security benefits, and leave heirs with more tax-efficient assets.
Paladin believes this planning window has become even more valuable against today's broader economic backdrop. The United States continues to carry federal debt at historically high levels, while future tax laws remain subject to congressional action. Meanwhile, the 2026 Social Security Trustees Report projects that the Old-Age and Survivors Insurance Trust Fund reserves will become depleted in 2032 if Congress does not act, at which point continuing income would be sufficient to pay approximately 78% of scheduled benefits.[1][2][3]. If lawmakers do not enact changes before then, scheduled Social Security benefits could be reduced. While no one can predict future tax policy or legislative action, Beyer believes retirees should prepare for multiple outcomes rather than assume today's tax environment will remain unchanged.
"We can't control Washington," Beyer said. "We can't control future tax rates, inflation, or changes to Social Security. What we can control is how and when retirement assets are withdrawn. That's where thoughtful planning can have an enormous impact."
Using sophisticated retirement tax-planning software, Paladin Retirement Advisors analyzes thousands of withdrawal and Roth conversion scenarios to identify the most tax-efficient strategy for each household. In many cases, the analysis uncovers opportunities to substantially reduce projected lifetime taxes-not by taking additional investment risk, but by changing the sequence and timing of retirement withdrawals.
"People often think retirement planning ends once they stop working," Beyer added. "In reality, retirement is when one of the most important financial decisions begins. The choices made during the first five to ten years of retirement can influence taxes, Medicare costs, and retirement income for decades. That's why we believe retirees need more than an investment manager-they need someone who can help them thread the retirement tax needle."
As more Americans enter retirement over the coming decade, Beyer believes proactive tax planning will become just as important as investment management. The Roth Sweet Spot is not about avoiding taxes altogether; it's about paying taxes strategically, at a time when retirees may have the greatest flexibility and the most planning options available.
About Paladin Retirement Advisors
Paladin Retirement Advisors is an independent retirement planning and wealth management firm headquartered in Newtown, Pennsylvania. The firm specializes in retirement income planning, tax-efficient retirement strategies, investment management, Social Security optimization, Medicare planning, and comprehensive financial planning. Paladin's mission is to help individuals retire with confidence by maximizing income, minimizing unnecessary taxes, and preserving wealth throughout retirement.
For more information, visit retirepaladin.com.
Advisory services are offered through JSBJ Enterprises, Inc. (dba Paladin Retirement Advisors), an Investment Advisor in the State of PA. All content is for information purposes only. It is not intended to provide any tax or legal advice or provide the basis for any financial decisions. Nor is it intended to be a projection of current or future performance or indication of future results. Purchases are subject to suitability. This requires a review of an investor's objective, risk tolerance, and time horizons. Investing always involves risk and possible loss of capital. It is important that you do not use email to request, authorize or effect the purchase or sale of any security, to send fund transfer instructions, or to effect any other transactions. Any such request, orders, or instructions that you send will not be accepted and will not be processed. Insurance products and services are offered through Paladin Insurance Advisors, LLC. The text of this communication is confidential, and use by any person who is not the intended recipient is prohibited. Any person who receives this communication in error is requested to immediately destroy the text of this communication without copying or further dissemination.
1) Congressional Budget Office, "The Budget and Economic Outlook: 2026 to 2036," February 11, 2026. CBO projects federal debt held by the public at 101% of GDP in 2026, rising to 120% by 2036 and surpassing its previous post-World War II record.
CBO report
2) Internal Revenue Service, Publication 15-T, "Federal Income Tax Withholding Methods," 2026. The IRS states that Public Law 119-21 permanently extended the individual tax rates originally enacted by the Tax Cuts and Jobs Act.
IRS Publication 15-T
3) Social Security Administration, "Social Security Board of Trustees: Projection for Combined Trust Funds Remains Consistent with Prior Year," June 9, 2026. The Trustees project depletion of the OASI reserves in the fourth quarter of 2032, with 78% of scheduled benefits payable at that time.
SSA 2026 Trustees announcement
Contact Information
Paladin Retirement Advisors
Jeff Beyer
215-860-3101
[email protected]
retirepaladin.com
SOURCE: Paladin Retirement Advisors
View the original press release on ACCESS Newswire
P.McDonald--TFWP