RIO
-0.3300

“Europe’s capitulation” has become a popular shorthand for policy drift, budget fatigue, and messy coalition politics. Yet on the ground and in Brussels, the picture is more complicated. Europe has locked in multi-year macro-financial support for Ukraine, is funnelling windfall profits from frozen Russian assets to Kyiv, and has extended protection for millions of displaced Ukrainians. At the same time, gaps in air defence, artillery supply and manpower—plus energy-system devastation—continue to shape Ukraine’s battlefield prospects and its economy. The fate of Ukraine will hinge less on a sudden European surrender than on whether Europe can sustain, coordinate, and accelerate support while managing domestic headwinds.
Money and political guarantees, not a white flag
The EU’s four-year Ukraine Facility—up to €50 billion through 2027—was designed precisely to replace short, crisis-driven packages with predictable financing tied to reforms and reconstruction milestones. Beyond that baseline, member states agreed to capture and channel windfall profits generated by immobilised Russian sovereign assets, adding a new, recurring revenue stream to help service Ukraine’s debt and fund defence-critical needs. Accession talks have formally opened, giving Kyiv an institutional anchor point inside Europe’s legal and regulatory orbit even as the war continues. None of this resembles capitulation; it is a bet that strategic patience and budgetary endurance can outlast the Kremlin’s war economy.
Guns, shells and jets: the pace problem
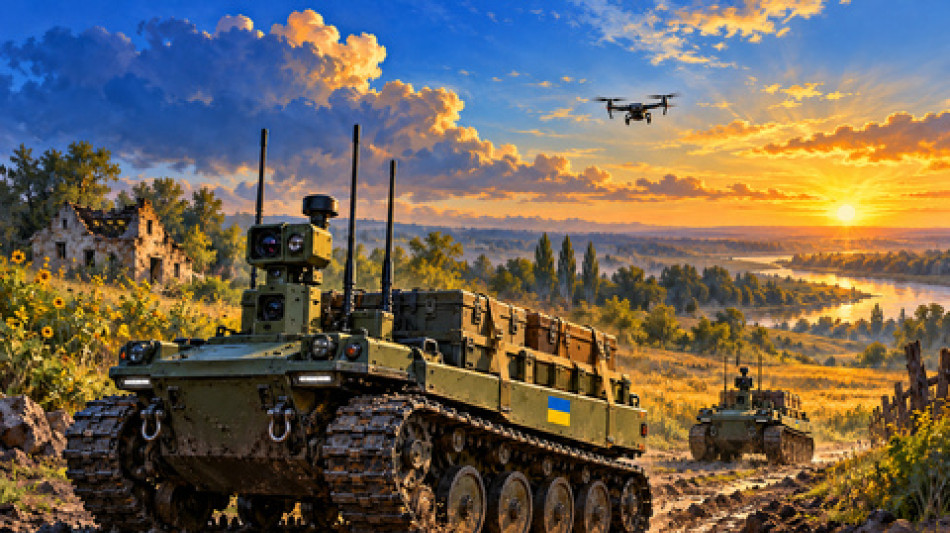
If Ukraine’s fate turns on combat power, Europe’s challenge is speed. A Czech-led initiative has become a central workaround to global shell shortages, aggregating ammunition from outside the EU and delivering at scale this year. Meanwhile, NATO governments have moved additional air-defence systems to Ukraine and opened the pipeline for F-16s, but the timing and density of deliveries matter: months of lag translate into increased damage to infrastructure and pressure on the front. Europe’s defence industry is expanding 155 mm output, but capacity reached the battlefield later than hoped, forcing Ukraine to ration artillery while Russia leaned on its larger stockpiles and foreign resupply.
Energy war: keeping the lights—and factories—on
Moscow’s winter-spring campaign of missile and drone strikes has repeatedly targeted power plants, substations and fuel infrastructure, degrading a grid that already lost most thermal capacity and leaving cities to cycle through blackouts. The immediate consequence is civilian hardship; the second-order effect is economic—factories halt, logistics slow, and government revenues suffer. Every delay in repairing large plants pushes Ukraine to rely on imported electricity, mobile generation and EU emergency equipment. As the next cold season approaches, the balance between new air defences, dispersed generation, and repair crews will determine whether critical services can be kept running under fire.
Manpower and mobilisation: a hard domestic trade-off
Ukraine has tightened mobilisation rules and lowered the draft age to sustain force levels. Those moves are politically and socially costly, but unavoidable if rotations are to be maintained and newly trained F-16 units, air-defence crews and artillery batteries are to be staffed. The calculus is brutal: without people, even the best kit sits idle; without kit, personnel face unacceptable risks. Europe’s role here is indirect but decisive—trainers, simulators, and steady flows of munitions reduce the burden on Ukraine’s society, shorten training cycles, and improve survivability at the front.
Refuge, resilience—and the long road home
More than four million Ukrainians remain under temporary protection across the EU, a regime now extended into 2027. Host countries have integrated large numbers into schools and labour markets, which improves family stability and builds skills but also creates a future policy dilemma: how to encourage voluntary, safe return when conditions allow, without stripping Ukraine of a critical labour force needed for reconstruction. The longer protection lasts, the more return requires credible security guarantees, jobs and housing back in Ukraine—another reason why European investment planning and city-level reconstruction projects will be as strategic as any weapons shipment.
Politics: cracks vs. consensus
European politics are not monolithic. A small number of leaders have advocated “talks now” and pursued freelance diplomacy with Moscow, drawing rebukes from EU institutions and many member states. But the broader centre of gravity still favours sustained support tied to Ukraine’s sovereignty and territorial integrity. That consensus is reinforced by practical security concerns: if Russia is rewarded for conquest, Europe’s eastern flank becomes less stable, defence spending must increase further, and deterrence becomes costlier over time. The debate, therefore, is not whether to support Ukraine, but how fast, how much, and with what end-state in mind.
Scenarios for Ukraine’s fate
Scenario 1: Sustained European backing, measured gains.
If macro-financial flows remain predictable, air defence density rises, and artillery supply meets operational demand, Ukraine can stabilise the front, shield key cities and infrastructure, and preserve manoeuvre options. Economic growth would remain modest but positive under IMF programmes, with reconstruction projects accelerating where security allows.
Scenario 2: Stagnation and a frozen conflict.
If delivery timelines slip and political bandwidth narrows, Ukraine could face a grinding positional war—no immediate collapse, but mounting strain on the energy system, the budget and demographics. A de-facto line of contact hardens, complicating EU accession and reconstruction while keeping risks of escalation high.
Scenario 3: Coercive “peace” under fire.
Should air defences and ammunition fall short while Russia intensifies strikes, pressure for a ceasefire on Russia’s terms would grow. That would not end the war; it would reset it. Without enforceable security guarantees and rearmament, Ukraine would face renewed offensives after any pause, while Europe would inherit a wider, more expensive deterrence mission.
What will decide the outcome
Three variables will decide whether talk of “capitulation” fades or becomes self-fulfilling: (1) delivery tempo—how quickly Europe translates budgets and declarations into interceptors, shells, generators and spare parts; (2) industrial scale—how fast EU defence production closes the gap between promises and battlefield need; and (3) political stamina—whether governments can explain to voters that the cheapest long-term security for Europe is a sovereign, defended Ukraine integrated into European structures. On each front, Europe still holds agency. Ukraine’s fate is not sealed; it is being written, week by week, by logistics, legislation and the will to see the job through.