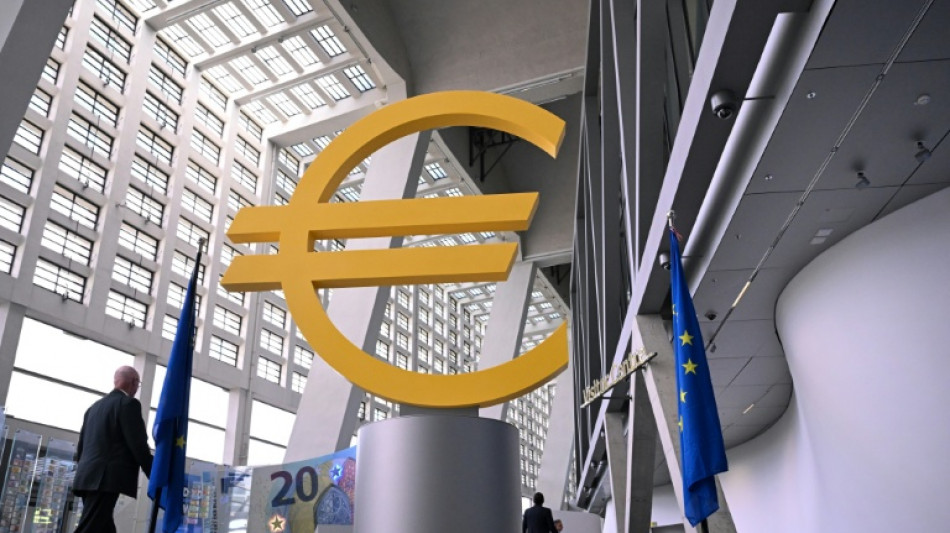
ECB meets, weighing a tricky balance between savers and spenders / Photo: © AFP
The European Central Bank is widely expected to raise its key interest rate after a two-day meeting starting Wednesday, trying to push down inflation without denting economic growth.
Higher borrowing costs put a damper on spending plans for both firms and households, but savers could benefit from the better returns on their funds, particularly if they hold bonds.
Here's a look at the winners and losers when central banks tighten monetary policy.
- Costly credit -
Most analysts say a quarter-point hike to the ECB's deposit rate to 2.5 percent is a near certainty, as it tries to keep the surge in energy prices from the Iran war from snowballing into widespread inflation.
The US Federal Reserve is also under market pressure to start tightening to get inflation down to its two-percent target, with government bond yields soaring recently -- though President Donald Trump insists they should be lowered.
In practice, the ECB raises its deposit rate, the interest it pays to commercial banks for parking their excess cash with it.
The Fed benchmark, the Federal Funds Rate, sets the interest rate big banks use to lend or borrow their excess reserves to one another.
In each case that translates into higher rates throughout the financial system, since banks will demand higher returns for all sorts of lending compared to these risk-free benchmarks.
Mortgages, consumer credit and other loans become more expensive, forcing consumers to limit spending and companies to rethink investment plans.
Economic activity often slows as a result, easing inflationary pressures that are percolating throughout the economy -- but not those from external shocks such as energy prices due to the Iran war.
- Spending power curtailed -
"People are going to see mortgage rates rise if they are negotiating a new loan or refinancing existing ones, so they lose some of their spending power," said Frederik Ducrozet, head of strategy and macro research at Pictet Wealth Management.
In some countries, mortgage rates "float" in line with market rates, so the impact of higher borrowing costs are felt immediately.
That risks weighing on growth, but the ECB may feel it has little choice because the surge in fuel costs "is a real problem", Ducrozet told AFP.
"The ECB is afraid of knock-on effects, with inflation taking root across Europe on the domestic front, for example via salary negotiations," he said.
But raising rates preventively "carries growing risks for the eurozone economy", said Christophe Boucher, investment director at ABN AMRO Investment Solutions.
"If you expect rates to raise even more, and if the yields on the long-term debt of France and other European countries continue to climb, it tightens monetary conditions even more than central bank hikes alone," Ducrozet said.
- Savings more attractive -
Higher rates often make it more expensive for governments to raise money from bond sales, a pressing concern as debt and deficit levels remain high in several European countries.
Yields on long-term government debt have risen to levels not seen since the 2008 global financial crisis in the United States, France and Japan.
Paris last week had to sharply increase the interest rate offered in its monthly sale of benchmark government bonds -- money that could otherwise be spent on education or defence.
That means a better return for investors willing to park their money long term -- as long as inflation remains contained.
Higher market rates can also benefit insurance companies and others who keep their funds in term deposits, which often include corporate and government bonds.
Banks themselves see their net interest margins improve, since the interest they earn on newly extended credit accumulates faster than the interest they are paying on customer deposits like savings accounts.
And of course, they are getting more from the ECB when they take advantage of the deposit facility for their excess cash.
J.Ayala--TFWP