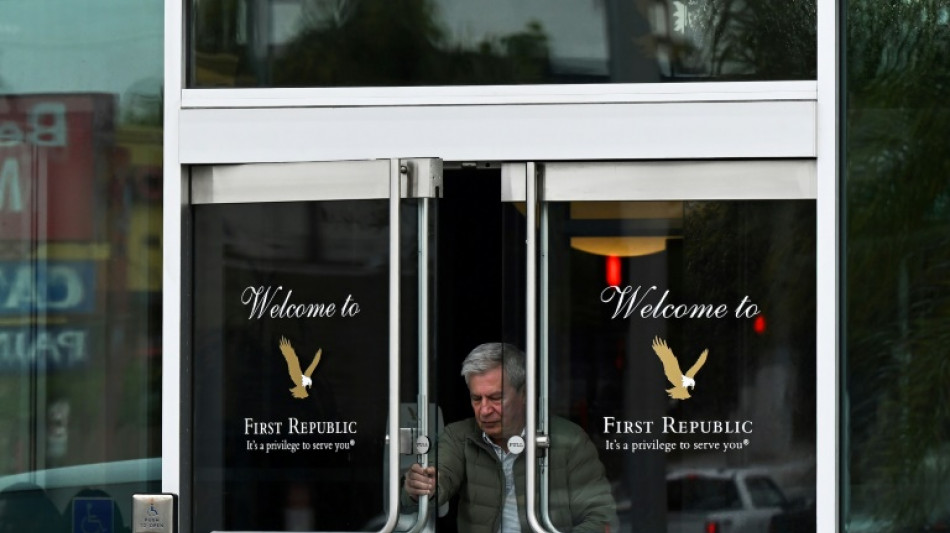
A vital pillar of US economy, regional banks soldier on / Photo: © AFP/File

When Barrett Hill, a farmer in the US state of Illinois, needs a loan for land or new equipment, a simple phone call is all that it takes.
"My banker makes my life way easier," Hill told AFP, adding that he grew up with his contact at Peoples State Bank of Newton, which has eight branches in the Midwestern state.
Shaken by the banking crisis and jitters among some clients, US regional and community banks are determined to remain key players in financing small businesses and individuals.
"We are relationship focused," says Brad Bolton, chief executive of Community Spirit Bank, an institution in the southern US with $195 million in assets and six branches in Alabama and Mississippi.
"My customers know me, and I know them. I know their financial standing," he says.
In the US, community banks account for 60 percent of loans to small businesses and 80 percent to farmers, according to the Independent Community Bankers of America, a trade group that represents small and midsized US banks.
US banking giants with global operations, such as JPMorgan Chase and Citigroup, are the most widely known. But there are over 4,700 banks and 4,760 credit unions in the United States whose deposits are guaranteed up to a threshold by the Federal Deposit Insurance Corp., which dates back to rampant bank failures during the Great Depression (1929-1941).
Small and medium-sized banks offer all the basic services, although it may be difficult for them to offer competitive rates on home loans, said Julie Hill, a banking expert at the University of Alabama.
They are very strong in lending to small businesses when risk analyses are not easily done by computer.
"It's much easier to have a person assess the business plan," she said, adding that big banks rely on "economy of scale and financing for rather large businesses."
- Freedom to experiment -
Another advantage of midsized regional banks, in her eyes, is that authorities can let them experiment, such as with cryptocurrencies.
"If you have only a large handful of really big banks, the government will be hesitant to let them experiment," she said.
The downside, she added, is that regional banks are not considered big enough for the government to save in times of trouble.
"Even if they think their bank is in pretty good health, is well run, the bigger depositors might get worried," Hill said.
After the failure of three medium-sized US banks -- Silvergate, Silicon Valley Bank and Signature Bank -- other publicly traded institutions with similar profiles worried about customers withdrawing their money en masse.
First Republic's stock has lost 88 percent since March 8, and its fate was still up in the air on Wednesday, despite help from the authorities and rival institutions.
PacWest has lost 62 percent over the same period, Western Alliance 55 percent and Zions Bank 35 percent.
The president of Zions Bank, the 36th-largest US bank by assets, acknowledged Tuesday at an American Bankers Association conference that the previous week had "really been busy" between conversations with employees, customers and the media -- all while putting in place contingency funding plans.
Silicon Valley Bank, a competitor, focused on a very specific clientele -- tech entrepreneurs -- and was "an outlier compared to all of the other banks in the United States," said Zions Bank CEO Scott Anderson.
Some customers withdrew their money before bringing it back, he recounted. "They want to make sure they can do that. And obviously we're there to help them with that when they have those questions."
Heads of other smaller institutions present at the conference also sought to be reassuring.
"We had a few phone calls, but really it wasn't that much," said Dan Robb, chief executive of Jonesburg State Bank in Missouri.
"I think people do believe in the safety of the system and feel that we are resilient."
"Every community bank that I have talked to, there has been no large outflows of deposits," Bolton said. "And matter of fact, we've had a deposit inflow."
"My bank has been here for 115 years, and I have full intention of being here another 115 years. And my customers know and understand that."
W.Lane--TFWP