REITs, Institutional Capital, and Canada's Housing Future: Why Attracting Smart Money Matters

TORONTO, ON / ACCESS Newswire / March 23, 2026 / Canada's housing crisis is well-documented: soaring construction costs, stalled development pipelines, and a chronic shortfall of new supply stretching from Halifax to Vancouver. While much of the policy debate has focused on zoning reform and government-led affordable housing programs, a quieter conversation is gaining traction among development leaders - one that centres on the role of Real Estate Investment Trusts (REITs) and institutional capital in solving Canada's most persistent urban challenge.
Ladan Hosseinzadeh Sadeghi, President & CEO of Sky Property Group Inc., is among those pushing this conversation to the forefront. With years of experience navigating the complexities of high-density residential development across the Greater Toronto Area, Hosseinzadeh Sadeghi argues that unlocking institutional investment is not just an economic opportunity - it is a housing policy imperative.
"We cannot build our way out of this crisis with small capital alone," said Hosseinzadeh Sadeghi. "The scale of what Canada needs - hundreds of thousands of new rental and ownership units over the next decade - requires institutional partners who can commit long-term capital, absorb development risk, and operate at volume. REITs and pension funds are uniquely positioned to do this. The question is whether our regulatory environment is inviting them to the table or pushing them away."
The Scale of the Problem
Canada's housing shortfall is staggering. The Canada Mortgage and Housing Corporation (CMHC) estimates the country needs to build approximately 3.5 million additional homes by 2030 just to restore affordability to 2004 levels. Municipal approval timelines, rising development charges, high interest rates, and labour shortages have all conspired to slow the pace of new construction precisely when it needs to accelerate.
For individual developers and smaller firms, these conditions represent existential risk. A project that made financial sense at a 4.5% lending rate and 2021 construction costs may be deeply underwater today. This is where patient, large-scale institutional capital - the kind held by Canadian pension funds like CPPIB, OMERS, and the Ontario Teachers' Pension Plan, as well as publicly listed REITs - can play a stabilizing role.
REITs as a Housing Solution, Not a Villain
REITs have become politically controversial in Canada, often framed as corporate landlords squeezing renters for profit. Hosseinzadeh Sadeghi acknowledges the legitimate concerns around tenant displacement and rent increases but pushes back on the narrative that institutional ownership is inherently opposed to housing affordability.
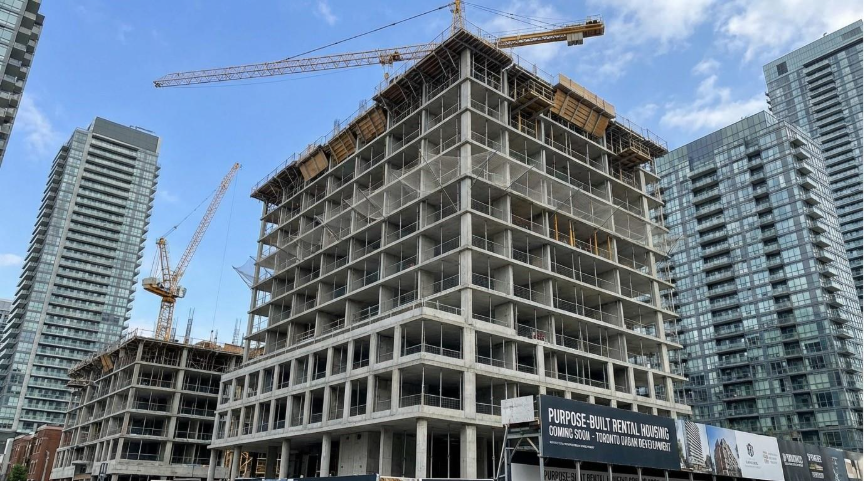
"There is a meaningful difference between a REIT that buys and holds existing rental stock - sometimes at the expense of existing tenants - and one that finances the construction of net new rental supply," she said. "Canada needs more of the latter. When a large institutional investor finances a 500-unit purpose-built rental tower, they are adding supply to the market. That is the outcome we need. Policy should distinguish between these two activities and actively encourage the one that creates new homes."
Several Canadian REITs have been moving in this direction. Purpose-built rental development has become a growing segment of the REIT market as interest rate stabilization makes long-term yield plays more attractive again. Firms like Killam Apartment REIT, InterRent REIT, and Boardwalk REIT have publicly committed capital to new development pipelines, signalling that the sector is evolving beyond pure asset acquisition.
The Policy Environment: Getting It Right
For institutional capital to flow into housing development at scale, the policy and regulatory environment must align with investor timelines and risk profiles. Hosseinzadeh Sadeghi identifies three priority areas where Canadian governments at all levels must act.
Certainty and speed in approvals.
"Institutional investors plan in decades, but they won't deploy capital into markets where a rezoning application can take five to seven years," she said. "Ontario's recent moves to streamline approvals are a step forward, but municipalities need to be full partners in that transformation. The regulatory risk premium attached to Canadian development is simply too high right now."
Development charge reform.
Municipal development charges across the GTA have more than doubled in the past five years in some jurisdictions. For purpose-built rental, where revenues are capped by market rents rather than sale prices, these charges can make projects financially unviable. Several provinces and municipalities have begun introducing exemptions or deferrals for purpose-built rental, and Hosseinzadeh Sadeghi argues this approach should be expanded and standardized nationally.
Tax treatment of rental housing investment.
Canada's current tax framework was largely designed around an owner-occupier housing model. Modernizing capital cost allowance rules and removing GST from new purpose-built rental construction - a measure the federal government has taken steps toward - directly improves the return profile for institutional investors and can unlock billions in stalled development capital.
"We need to be honest about what we're asking institutional investors to do," said Hosseinzadeh Sadeghi. "We want them to absorb long development timelines, high upfront costs, and complex regulatory environments, and to do so while keeping rents as affordable as possible. That is a lot to ask. Policy has to make the math work, or the capital will go elsewhere."
The Opportunity in Uncertainty
Despite the challenges, Hosseinzadeh Sadeghi sees the current moment as genuinely promising. The Bank of Canada's rate-cutting cycle has improved borrowing conditions for long-duration real estate investments. Federal and provincial housing programs are injecting meaningful subsidy into affordable and mixed-income development. And a growing cohort of sophisticated institutional investors is actively looking for opportunities in the Canadian residential market.
"There is real appetite out there," she said. "International pension funds, domestic REITs, insurance companies with long-term liability profiles - they all see the fundamentals of Canadian housing. Strong population growth, urbanization, undersupply. The demand drivers are there. What we need now is the policy clarity and the partnership models to channel that capital productively."
Sky Property Group Inc. has itself been deepening relationships with institutional capital partners as it expands its portfolio of high-density residential projects across the GTA. Hosseinzadeh Sadeghi sees collaborative models - where institutional investors provide capital and long-term ownership while experienced developers like Sky Property Group provide land, relationships, and development expertise - as the most viable path forward.
"This is not a zero-sum game between developers, investors, and renters," she said. "Done right, institutional capital in housing is how Canada closes the supply gap. The alternative - waiting for governments to fund it all or hoping small builders can scale fast enough - is not working. It is time to bring serious capital to a serious problem."
About Sky Property Group Inc.
Sky Property Group Inc. is a Toronto-based real estate development and property management firm specializing in high-density residential development and land assembly across the Greater Toronto Area. Led by President & CEO Ladan Hosseinzadeh Sadeghi, Sky Property Group is committed to delivering thoughtful, community-centred development that addresses Canada's housing needs.
Media Contact:
Ladan Hosseinzadeh Sadeghi
[email protected]
SOURCE: Sky Property Group Inc.
View the original press release on ACCESS Newswire
W.Lane--TFWP