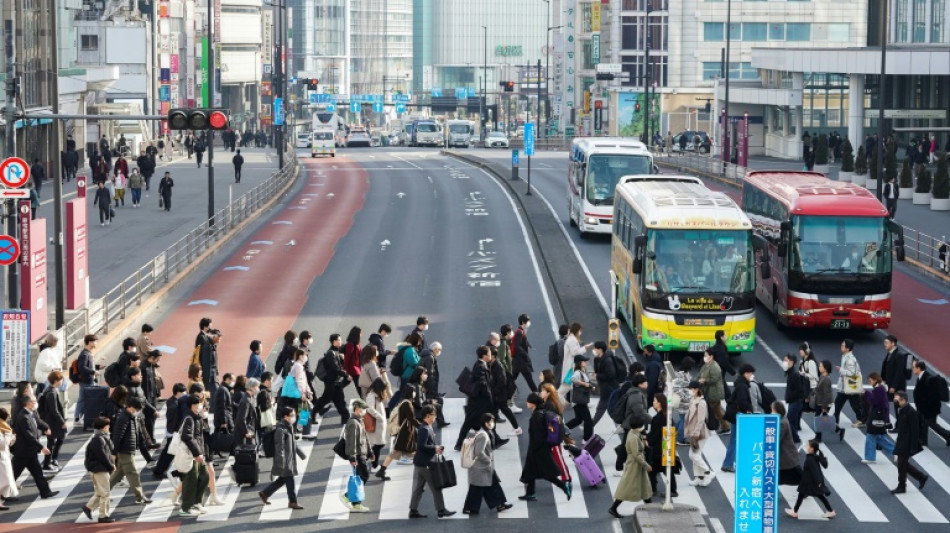
Easy does it: The Bank of Japan's experiment / Photo: © AFP
The Bank of Japan on Tuesday announced a seismic change in direction on Tuesday, hiking interest rates for the first time in 17 years.
The move represents an unwinding of an ultra-loose -- and maverick -- policy aimed at putting Japan's "lost decades" of stagnation and deflation behind it.
- 'Ambitious goal' -
The last time the BoJ raised interest rates was in 2007, but its war against deflation began in earnest in 2013 under then-prime minister Shinzo Abe.
"Abenomics" combined generous government spending and central bank monetary easing.
The BoJ spent vast amounts on bonds and other assets to pump liquidity into the system, targeting inflation of two percent that policymakers hoped would fuel growth.
It was "an extremely ambitious goal" and it didn't work right away, said Kazuo Momma, an economist at Mizuho Research and Technologies.
"Having failed to achieve the target within a committed two-year period, the BoJ had no other choice than to pursue further stimulative measures including the negative interest rate," Momma told AFP.
- Spur lending -
The negative interest rate of -0.1 percent -- hiked to between zero and 0.1 percent on Tuesday -- had been in place since 2016, effectively charging banks to keep their money at the Bank of Japan.
The hope was banks would loan out their capital instead, boosting economic activity.
The same year, bank policymakers introduced another measure, which Momma called "even more unconventional": yield curve control.
That consisted of buying as many or as few 10-year government bonds as necessary to keep their yields steady at zero, in order to stimulate lending in the real economy.
On Tuesday, this too was scrapped, along with the purchase of risk assets such as exchange-traded funds (ETFs), with the BoJ saying they had "fulfilled their roles".
- Crisis averted? -
The BoJ's stance has put major pressure on the yen.
But some say it met its aims, helping Japan escape deflation while providing better conditions for the BoJ's hoped-for "virtuous cycle" of higher wages and spending.
Overall, the consensus is that the economy would have fared worse without the measures, said Louis Kuijs, chief economist for Asia Pacific at S&P Global Ratings.
Due to downward pressure on growth and prices, growth "would have been weaker and significant deflation may have occurred if the BoJ had not eased monetary policy," he told AFP.
- 'Zombie' companies -
But Momma said that the policy might also have led to a "lack of fiscal discipline and inefficient allocation of resources through keeping non-viable firms alive".
One research company found that the number of "zombie" companies jumped by around a third in Japan after the Covid pandemic.
Monetary easing can also exacerbate social inequality, and "tends to distort financial markets", Kuijs warned.
Some economists, such as former BoJ board member Sayuri Shirai, still think factors including weak consumption make sustained two-percent inflation a long shot.
"There is no way to justify that two percent is achievable in terms of Japan's inflation environment and wage environment," she said.
- Wasted progress? -
If done too aggressively, the risks of moving away from years of monetary easing are high.
The BoJ "worries that if it tightens monetary policy, economic growth, wage growth and prices will fall again, wasting the recent progress," Kuijs said.
Moving too quickly could also see a flight of capital from elsewhere into Japan by investors seeking higher returns, potentially destabilising financial markets.
"Governor Ueda has stressed that, while there are risks of tightening too late, the risks of tightening too early are larger," Kuijs said.
S.Rocha--TFWP