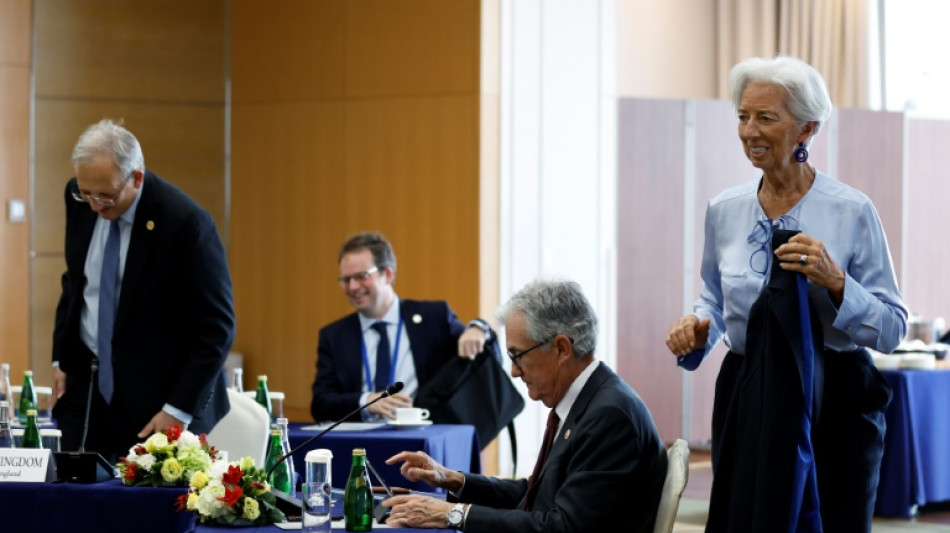
Did central banks break inflation? Some economists have doubts / Photo: © POOL/AFP/File
Central bankers who orchestrated the wave of interest rate hikes over the past two years, hoping to avoid a painful inflationary spiral, are now facing an uncomfortable question: Were their moves helpful?
The debate is heating up as European Central Bank policymakers meet this week, with many observers now expecting its benchmark lending rates to start coming down by this summer.
Governors at the US Federal Reserve are also weighing cuts for later this year, fanning hopes that the price surges seen in the wake of Covid-19 lockdowns and Russia's war on Ukraine have been brought under control.
But some economists argue that the spikes were only temporary -- and that inflation would have eased anyway, whether or not central banks tried to contain it with tighter monetary policy.
"It was not because of Fed action that the prices of cars, oil, food, or the host of other goods affected by supply-side interruptions came down, but because the underlying shortages were at least partially resolved," said Nobel Prize-winning economist Joseph Stiglitz.
Higher rates, however, are often the tool of choice by central bankers to increase borrowing costs for business, which can often spark an increase in jobless rates.
Households, meanwhile, are suddenly confronted with higher mortgage and housing costs, leading them to curb spending and drive down inflation through a fall of demand.
For Stiglitz and other critics, inflation was not being driven by increased demand -- which can be influenced more directly by the cost of credit -- but by supply constraints due to Covid and the Ukraine war.
"In many ways the Fed made things worse. It was more difficult to make the investments required to alleviate shortages," Stiglitz wrote in an essay for The American Prospect this month.
- 'Irony' -
Alan Blinder, an economist at Princeton and a former Fed vice chairman, agreed that global economic shocks -- by nature temporary -- stoked the inflation they have now eased even as economic growth on both sides of the Atlantic remains relatively robust.
"What the central banks did went in the right direction for sure, but it was of secondary importance," Blinder told AFP.
"The irony is that they got more blame than they deserved for letting inflation get out of control, and now they are getting more credit than they deserve for bringing it down," he said.
Other economists counter that it was massive Covid stimulus spending, from direct payouts to unemployment and business support, that flooded economies with money likely to drive prices higher.
That view was countered in June 2022 by Fed chairman Jerome Powell, who discounted the impact of government pandemic aid but insisted nonetheless that sharply higher interest rates were necessary -- even if it meant a recession.
For Stiglitz, Powell and his supporters were effectively prescribing economic pain for millions: "By killing the economy, there would be no excess demand, and by definition (in their minds) no inflation," he wrote.
- Higher wages? -
Some proponents of the rate hikes argue that regardless of the source of inflation, unless central bankers showed they were serious about tackling it, expectations of persistent and widespread price increases would only grow.
"Without a tightening, economic agents could have anticipated inflation would have stayed high," Benoit Mojon, head of economic analysis at the Bank of International Settlements, wrote in a December report.
Those price hikes could have rippled throughout the economy "and resulted in higher wages", he wrote.
Wage pressure has indeed been restrained in recent months, bolstering hopes of a "soft landing" for the US and European economies in which inflation eases while growth stays solid.
Weighing how much of that success is due to central bank policy is likely to fuel debates for months as economists study the unprecedented impacts of Covid and two years of intense war on Europe's doorstep.
In a recent study, Allianz Trade estimated that Federal Reserve action accounted for 45 percent of slowing inflation, with the rest the result of supply chains returning to normal across the planet.
"You could analyse that by saying everyone was right to an extent," said Maxime Darmet, an economist who authored the study.
"On the other hand you could say that those who think the inflation was only temporary completely ignore the impacts of central banks," he told AFP.
P.Grant--TFWP