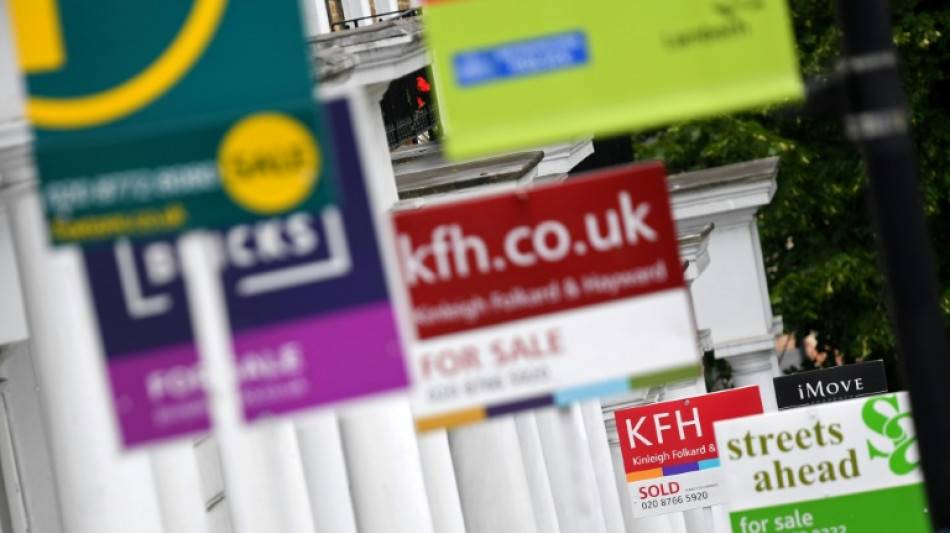
High inflation rattles UK home loan market / Photo: © AFP

Britain's retail lenders are withdrawing fixed home-loan products, as elevated inflation sparks fears of more Bank of England interest rate hikes and worsens the cost-of-living crisis.
UK banks mostly offer mortgages with a fixed interest rate for a set period -- typically two to five years -- but after expiry this becomes variable or a new rate is fixed in line with prevailing market conditions.
However, recent inflation data sparked speculation that the central bank will ramp up its key interest rate even higher to contain stubbornly high inflation.
That could further squeeze living standards and spell more gloom for Prime Minister Rishi Sunak's Conservative government before a general election expected next year.
- Mortgages pulled -
"Mortgages are being pulled, and then coming back to the market at a higher rate," said Sarah Coles, head of personal finance at stockbroker Hargreaves Lansdown.
HSBC joined the fray on Thursday, suspending certain home loans as it also sought to cope with significant new demand but stressed there was no change for existing customers.
Nationwide, one of the country's biggest home loan providers, was among a growing number of banks lifting product rates.
The total number of available mortgage products has meanwhile fallen by about five percent in just under one month, according to data provider Moneyfacts.
"This has been going on ever since the news emerged a couple of weeks ago that core inflation had risen," Coles told AFP.
The BoE last month lifted its key interest rate to 4.50 percent, its 12th increase in a row.
Retail lenders tend to match the central bank's increases to borrowing costs, sparking higher loan repayments, weighing on house prices and denting economic activity.
Although UK inflation slowed to a 13-month low in April, it remains elevated at 8.7 percent as soaring food bills offset weaker energy costs -- and is still more than four times the BoE's 2.0-percent target.
And core inflation, which strips out volatile energy and food, accelerated to 6.8 percent or the highest since 1992.
That cemented expectations of another BoE rate hike, with some investors predicting it could reach 5.5 percent by year-end.
The data also sent the UK government's long-term borrowing costs -- used as a reference for mortgage products -- jumping.
The yield on the 10-year UK government bond briefly rose not far from levels hit in October following unfunded tax cuts that sank the short-lived administration of Sunak's predecessor Liz Truss.
Average two-year fixed mortgage rates had hovered close to two percent in recent years, but rose sharply during the Truss premiership and before the BoE began lifting rates in December 2021.
And they gained about 0.5 percentage points over the last month to approach an average fix of six percent according to Moneyfacts.
That means that many Britons reaching the end of their current fixed home loans are forced to accept higher rates with far bigger monthly repayments.
- Financial problems -
Hargreaves Lansdown estimates 16 percent of Britons are already struggling to meet monthly mortgage repayments.
"Anyone whose deal comes to an end this year is set to see their monthly payments increase by an average of £192, but almost two-thirds of people said this would cause them financial problems," said Coles.
Many Britons "may need to extend (the term of) their mortgage for it to remain affordable, which will keep monthly payments lower, but will mean paying more interest over the long run".
Coles added that "in extreme circumstances" some may need to consider "selling up and downsizing" and warned this would hit the property market.
Consumers' incomes will take a big hit as they struggle to refinance, according to AJ Bell investment director Russ Mould.
The BoE is meanwhile attempting to bring down inflation in the long run.
"Higher mortgage rates mean higher interest costs and higher interest costs mean lower disposable income," he told AFP.
"The choice is between higher interest rates or inflation -- or possibly both," Mould cautioned.
M.McCoy--TFWP