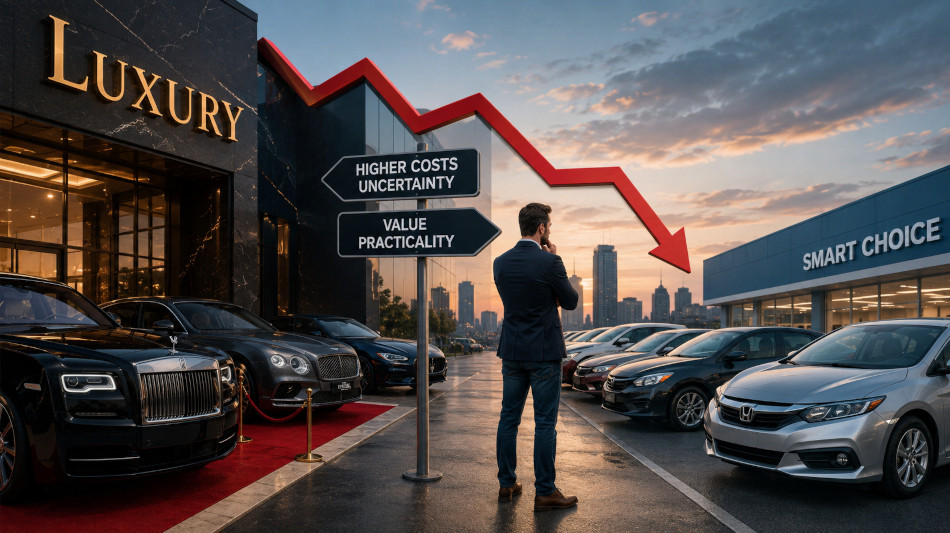
Luxury car buyers trade prestige for mainstream value
For much of modern motoring, the luxury-car business rested on a straightforward promise. A prestigious badge offered access to richer materials, quieter cabins, superior performance and technology that ordinary vehicles could not match. In 2026, that promise is becoming harder to defend. Increasing numbers of American buyers are discovering that a generously equipped mainstream vehicle can deliver most of the comfort, digital capability and everyday refinement they want, while leaving tens of thousands of dollars in their bank accounts.
The result is not simply a temporary response to difficult economic conditions. It is a structural challenge to the traditional premium-car formula. Features that once justified a step into a luxury showroom have spread rapidly through the wider market. Large digital displays, advanced driver assistance, connected services, panoramic roofs, sophisticated lighting, premium audio systems and heated rear seats are no longer reliable markers of exclusivity. In many cases, they are available in family SUVs carrying mainstream badges.
Premium market share is moving in the wrong direction
Excluding direct-to-consumer marques, premium vehicles represented 13.3 per cent of new-vehicle sales during the first half of 2026. That was down from 13.8 per cent in the corresponding period of 2025 and marked the smallest premium share recorded since 2020.
The clearest movement can be seen among SUV buyers. During the first six months of the year, 32 per cent of consumers replacing a midsize premium SUV purchased a vehicle from a mainstream brand. The average transaction price for the mainstream midsize SUV was approximately $51,500, compared with an average of $70,600 in the premium segment they had left.
That difference of about $19,100 is large enough to transform the purchasing calculation. Buyers are not necessarily surrendering space, equipment or perceived sophistication. They are deciding that the additional cost of the luxury badge no longer produces a sufficiently visible or valuable improvement.
Similar behaviour is appearing elsewhere in the market. Around 30 per cent of owners replacing compact premium SUVs moved to mainstream brands, while the defection rate among consumers leaving compact premium cars reached 42 per cent. Many of those buyers chose another SUV rather than returning to a conventional saloon, confirming that the shift is primarily about value rather than a rejection of comfort or utility.
Younger buyers are less attached to the badge
The movement away from traditional luxury brands is strongest among younger consumers. Generation Z buyers display the highest propensity to move into mainstream vehicles, followed by Millennials. Older customers remain considerably more likely to replace one premium vehicle with another. Income also plays a decisive role. Households earning more than $200,000 a year show the strongest premium retention, while buyers earning less than $100,000 are more inclined to select a mainstream alternative. Yet the trend cannot be explained solely by financial hardship. Even affluent consumers are becoming more selective, waiting for the right model and the right offer rather than buying a premium car simply because they can afford one.
This change in behaviour reflects a broader transformation in the meaning of status. Younger consumers often place greater value on software, connectivity, environmental performance and practical versatility than on the historic prestige of a manufacturer. A well-designed mainstream SUV with intuitive technology can therefore feel more contemporary than a luxury vehicle burdened by complicated controls, expensive options or an ownership experience that fails to match its price.
The experience gap has narrowed dramatically
The emotional advantage enjoyed by premium brands has also diminished. On a 1,000-point measure of owner satisfaction, the difference between premium and mainstream manufacturers has contracted to 29 points. In 2008, the gap stood at 66 points. That convergence is significant because luxury is ultimately an emotional purchase. Buyers may be willing to pay substantially more for a vehicle that feels exceptional every time it is driven, entered or even seen on the driveway. They are far less willing to pay the same premium when the difference is limited to a badge, a slightly richer dashboard and a longer list of costly options.
Mainstream vehicles have improved in areas that once created an immediate premium impression. Exterior design has become more confident, interiors are better finished and driver-assistance systems are increasingly sophisticated. Even details such as lighting performance, infotainment presentation and the sound of a closing door are no longer consistently superior in expensive vehicles. Electrification has accelerated this convergence. The development of electric vehicles encouraged manufacturers across the market to focus on screens, software, connectivity and advanced assistance systems. Technology became a substitute for traditional luxury, and the components needed to deliver it became available to a much wider range of brands.
At the same time, the growing complexity of digital systems has created new risks for premium manufacturers. A luxury vehicle that requires a lengthy set-up process, hides essential functions inside menus or suffers from inconsistent connectivity can quickly undermine its own promise of effortless sophistication. Expensive technology is not automatically premium technology. It must work more smoothly than the system in a cheaper alternative.
Affordability is reshaping the entire showroom
The migration towards mainstream brands is taking place against a difficult affordability backdrop. One measure placed the average transaction price of a new vehicle at $49,758 in June 2026. Although the overall market remains active, buyers are increasingly adjusting the type and price of vehicle they choose.
Financing conditions have magnified the pressure. The average monthly payment for a financed new vehicle reached a record $777 during the second quarter. Nearly 24 per cent of financed buyers selected loan terms of 84 months or longer, while 36.5 per cent committed to terms exceeding six years. Average interest rates for new-car loans remained above 6 per cent during the first quarter.
Longer loans can reduce the immediate monthly burden, but they also keep drivers in debt for more of the vehicle’s useful life and slow the accumulation of equity. For a household already facing higher housing, insurance and living costs, avoiding a $19,000 luxury premium can be more rational than stretching the same purchase across seven years. The strength of more affordable SUV categories reinforces the point. Sales of subcompact SUVs rose by more than 23 per cent in June, with an average transaction price close to $31,100. Consumers still want new vehicles, modern technology and the security of a factory warranty. They are simply searching more carefully for the point at which price, equipment and practicality meet.
Rising inventories are forcing luxury brands to spend more
Dealer inventories provide another warning. Premium-vehicle supply rose to almost 76 days in April before easing to approximately 67 days by July. Mainstream brands were carrying closer to 56 days of supply.
Luxury manufacturers have responded with stronger incentives. Premium discounts were running at about 7.3 per cent of the manufacturer’s suggested retail price by July, compared with approximately 6 per cent among mainstream brands. The difference may appear modest, but it reveals that premium manufacturers are working harder to convert interest into sales.
Heavy discounting creates a difficult strategic problem. Incentives can clear inventory and make monthly payments more attractive, but persistent reductions weaken the impression of exclusivity. They can also place pressure on residual values, frustrate recent buyers who paid more and train future customers to postpone purchases until another offer appears. Luxury manufacturers must therefore balance short-term sales against the long-term value of their brands. Producing too many vehicles and then discounting them aggressively risks turning a carefully cultivated premium product into an expensive commodity.
The vulnerable middle of the luxury market
The evidence does not suggest that luxury cars are disappearing. Wealthy customers remain willing to pay for genuinely exceptional design, craftsmanship, performance and service. Distinctive sports cars, flagship models and highly personalised vehicles continue to offer experiences that mainstream manufacturers cannot easily reproduce.
The greatest pressure is likely to fall on the accessible and middle sections of the premium market. These vehicles often share platforms, engines, software and components with less expensive models while relying heavily on design and brand identity to justify the difference. As mainstream alternatives become more polished, that premium becomes increasingly visible and increasingly difficult to defend.
This creates a polarised market. At the top, genuinely exclusive products can continue to command extraordinary prices. Below them, well-equipped mainstream vehicles offer compelling value. The conventional premium model positioned between those two extremes risks being squeezed from both directions.
Luxury must become more than a collection of features
Premium manufacturers now need to provide a clearer reason for buyers to remain loyal. More equipment alone will not be enough, because equipment can be copied. Larger screens will not be enough, because screens have become universal. Even additional power may have limited influence in a market where many electric vehicles already deliver rapid acceleration.
The defensible advantages are likely to be found in execution. A premium vehicle must be quieter, more comfortable and more intuitive. Its software must reduce effort rather than create it. Its materials must remain convincing after years of use. Its dealership, delivery, maintenance and digital-service experience must respect the customer’s time. Its residual value must support the original purchase decision. Above all, the vehicle must feel demonstrably better, not merely more expensive.
The current movement towards mainstream brands is therefore more than a search for cheaper transport. It represents a reassessment of what luxury means and what it is worth. Consumers have not lost their appetite for quality. They have become less willing to confuse quality with a badge.
U.Sellmer